Water mitigation is the emergency phase that limits damage by stopping water, extracting it and drying the structure, while restoration is the later phase that repairs or replaces what the water ruined. In Broomfield, CO the two often run under one roof but they are different jobs with different paperwork. Knowing which one you are in helps you talk to your insurer and compare scopes.
Short answer: mitigation is what you do now to keep the loss from growing. Restoration is what you do after the structure is dry to put the home back together.
Two phasesThe Phases Compared
| Topic | Mitigation | Restoration |
|---|---|---|
| Goal | Stop the loss from growing | Return the home to its prior condition |
| Timing | Immediately, as soon as it is safe | After the structure reads dry |
| Typical work | Shutoff guidance, extraction, drying, monitoring, removal of materials that cannot be saved | Drywall, insulation, flooring, trim, cabinets, primer and paint |
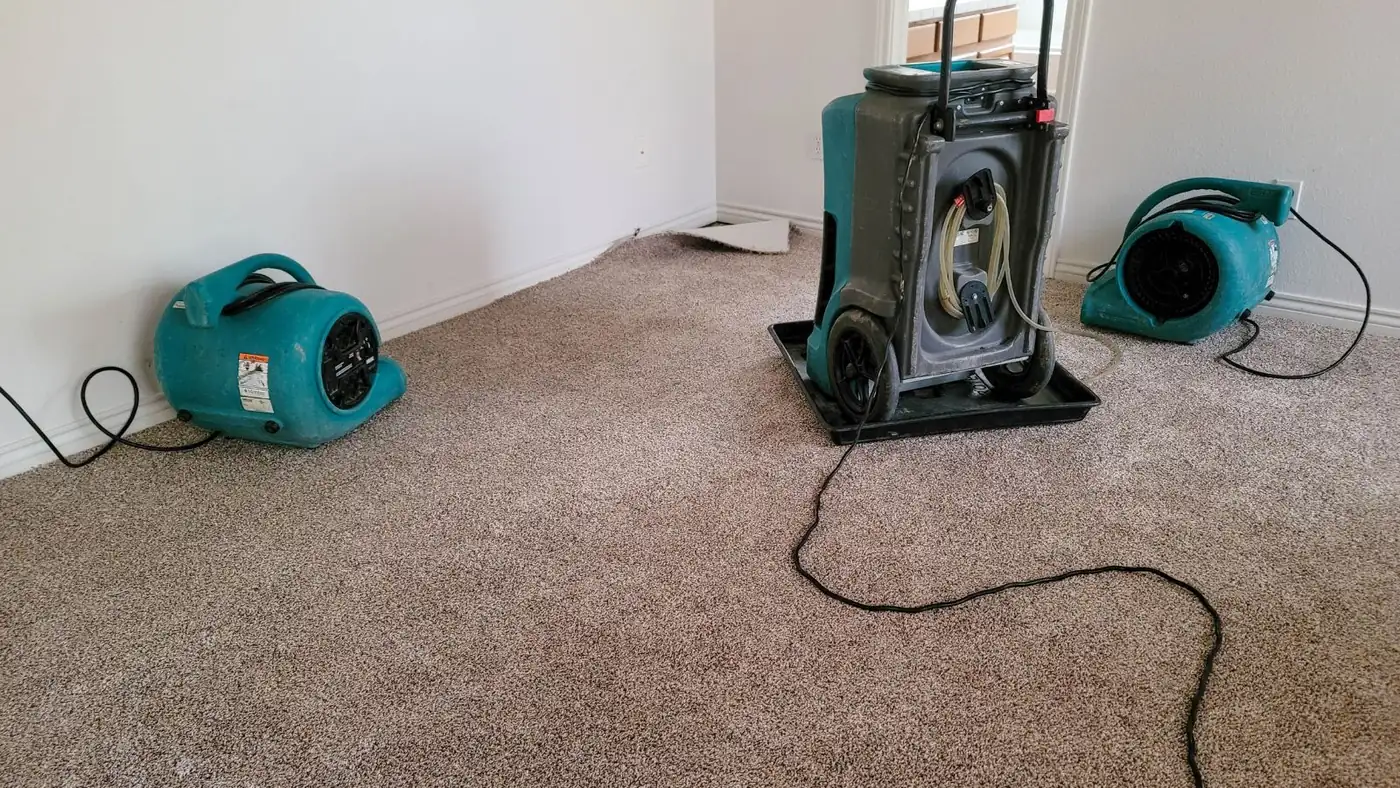
| Equipment | Extraction units, air movers, LGR dehumidifiers, moisture meters, thermal imaging | Standard rebuild tools and finishes |
| Paperwork | Moisture logs, photos, equipment records, list of removed materials | Scope of repairs, material choices, permits where required |
| Service page | Water mitigation | Water damage repair |
Some jobs need only mitigation, and some move straight to repair after a short dry-out.
Why Mitigation Comes First
Rebuilding over wet material locks the problem in. New drywall on a damp stud can lead to staining, swelling or growth, and the repair has to be done twice. A dry reading is the gate between the two phases.
Mitigation also keeps the claim from growing, which matters to you and to your insurer. Water that is left to spread increases what must be removed and repaired. Doing the early work quickly is a practical way to keep the later scope smaller.
Who Documents What
You
Photographs of the damage before anything moves, a list of affected rooms and belongings, and receipts for urgent expenses.
The mitigation crew
Moisture readings over several visits, equipment placed and removed, and which materials were taken out and why.
The repair contractor
The scope of rebuild work, materials, finish choices and any permits the work needs.
Your insurer
The claim file, the policy review and the adjuster's findings. You are entitled to ask for a copy of your policy.
Want the scope in plain terms?
Call and tell us what happened. We explain the mitigation and repair steps and the price before work starts.
How the Phases Line Up With a Claim
General insurance terms apply here, and your policy decides the details. An abrupt event is often treated differently from a slow leak, and flood is typically handled through a separate flood policy. Ask your insurer which category your loss falls into.
Make it safe
Stop the water if you can do so safely, then call your insurer and a mitigation company.
Document
Photograph the damage and keep samples of removed materials until the adjuster has seen them.
Mitigate
The crew extracts and dries, takes readings and keeps a log your insurer may ask to see.
Agree the scope
The repair scope is written, compared with the adjuster's view and explained to you.
Rebuild
Permits are pulled where needed and the repair work is carried out.
We cannot promise how a claim will go, and we do not name carriers or predict payouts. The best we can do is keep the records clear and the scope explained. That makes the conversation with your adjuster easier, and it keeps you from guessing at what was done.
Broomfield note: Permits and Policy Copies
The City and County of Broomfield Building Division says alterations, garage conversions, changes of use, structural repairs, drywall, and fire or flood repairs require permits. Permits belong to the rebuild stage, not the drying stage, so ask the division at 303-438-6370 (option 5) or [email protected] before the repair begins. Your contractor should tell you who pulls the permit.
The Colorado Division of Insurance handles consumer questions about policies. Ask your insurer for a copy early, before mitigation ends, so you know what the policy says about water damage and flood.
The division's guidance also separates flood from ordinary homeowners coverage. If you hold flood coverage, report the loss without delay and read the policy's notice terms, since the division's page states no deadline.
A Hypothetical Walk Through Both Phases
Picture a supply line that fails under a kitchen sink and wets the cabinet base, the floor and the bottom of a shared wall. In the mitigation phase, the water is shut off, extraction removes the standing water and the crew pulls the toe-kick and a strip of baseboard to dry the wall base. Readings are logged each visit until the numbers level out.
In the restoration phase, the wet cabinet base, a section of drywall and the damaged flooring are replaced, then primed and painted. The repair scope rests on the mitigation log, which shows what was wet and what dried. This is an illustration only, since every house and every loss differs.
Common Mix-ups Between the Phases
- Thinking dry to the touch means done. Only readings confirm that framing and subfloor are ready.
- Starting repairs before drying ends. The finishes may need to be redone if moisture is still in the wall.
- Throwing out materials before photos. Take pictures and keep samples until your insurer has seen them.
- Assuming one estimate covers both phases. Mitigation and repair usually have separate scopes and may change as the work opens up the structure.
If a scope changes mid-job, you should hear why before the work continues. A reasonable company explains what it found and what that does to the plan. That is how the price stays tied to the real condition of the house. Ask for any change in writing, with the reading or photo that prompted it, so both phases stay documented.
What Each Phase Does Not Do
- Mitigation does not rebuild finishes, and a dry house can still have open walls.
- Restoration does not fix plumbing, so a plumber handles the leaking pipe or fixture.
- Neither phase waterproofs a basement, which is a separate type of work we do not perform.
- Neither replaces mold testing or remediation where growth is found. See our mold remediation page for that path.
Electrical and sewage warnings
Water touching outlets, appliances or a panel, or any sewage involvement, means the utility or 911 gets the first call about electrical or gas risk, and the restoration line gets the second.
Choosing a Company for Each Phase
You can use one company for both phases or separate ones. Ask for the scope in writing and ask which published water damage standard the crews follow. We are licensed and insured, and our work spans the home market of ZIP codes 80020, 80021 and 80023, plus Louisville and Lafayette.
Extraction is part of mitigation, but mitigation also covers drying, monitoring and removing materials that cannot be saved. Water removal alone leaves moisture in walls and floors.
No. Some homeowners hire one company for mitigation and another for repair. The records from the first phase should pass cleanly to the second.
An abrupt event such as a failed supply line is often covered, and early mitigation is usually part of that conversation. Slow leaks often are not. Ask your insurer and read your policy.
Drywall and flood repairs both need a permit. Contact the Building Division before the rebuild begins and ask what applies to your scope.
Ask for a copy of the policy, since Colorado sets a short deadline for insurers to provide one. Then ask how your type of loss is classified and what notice the policy requires.
Water or mold in your home right now?
Call the 24/7 line and describe what you see. We explain scope and price before work starts.